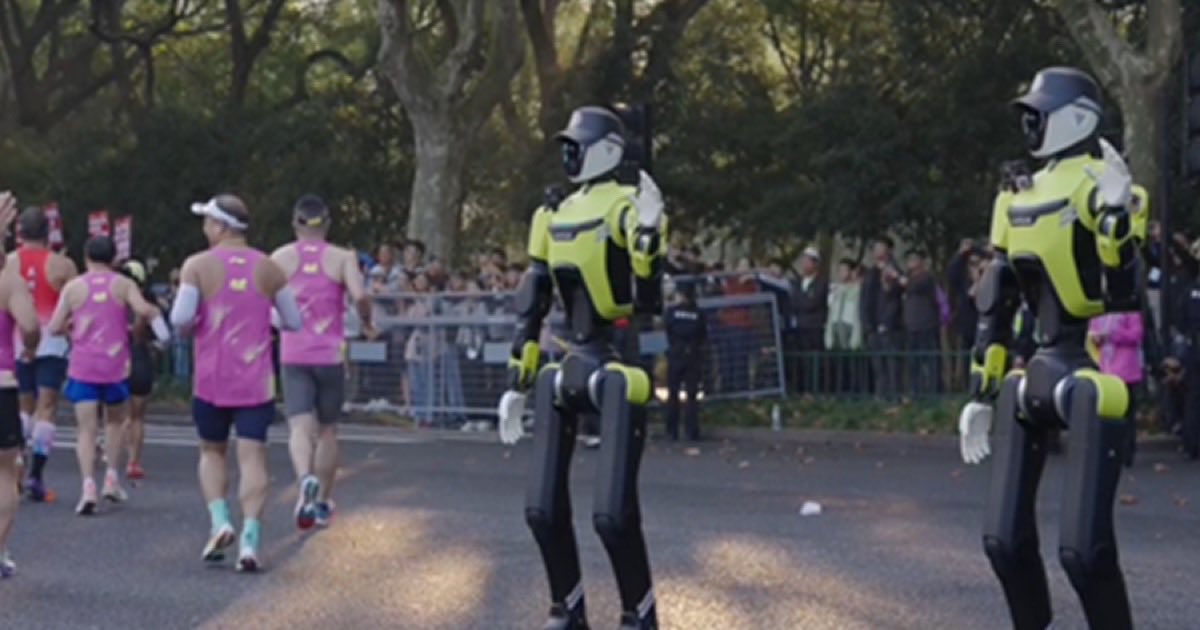
Unitree, China’s best-known humanoid robot maker, posted its first earnings since listing on Shanghai’s STAR Market: third-quarter revenue rose 69.9% year-on-year to 665 million yuan (about US$100 million), while net profit attributable to shareholders fell 17.4% to 112.7 million yuan. Reuters reports the miss was steep against expectations — analysts had forecast 224 million yuan, roughly double what the company delivered, as Unitree more than doubled its research spending in a single quarter.
The cost that ate the profit is the story. Quarterly R&D investment reached 127 million yuan, up 249.6% from a year earlier — 19.1% of revenue, up nearly 10 percentage points. Per the filing, the money is going into embodied-intelligence large models, computing capacity and team expansion. Revenue grew 70%; the spending needed to stay competitive in robot intelligence grew more than twice as fast.
Nine-month numbers hide the same trade-off
The first nine months of 2026 look rosier at first glance: revenue up 55.7% to 1.817 billion yuan, attributable net profit up 270.5% to 386.7 million yuan. But the profit-excluding-non-recurring-items figure fell 18.8% to 349 million yuan — the headline surge comes mostly from a large one-time share-based payment expense booked in the prior year, not from this year’s operations getting dramatically better. Operating cash flow for the nine months fell 54.7% to 193.7 million yuan while R&D spend rose 191%, per Robotico’s read of the exchange filing.
Unitree remains one of the few profitable domestic robot firms in a sector most of which has no clear commercial application yet. Whether that profitability survives 2027 depends almost entirely on whether the R&D bet converts into product differentiation or becomes a permanent cost of standing still.
A bellwether under maximum scrutiny
Reuters frames this filing as a market test for the whole wave of Chinese humanoid listings: investors are watching Unitree as the bellwether for whether embodied-AI valuations rest on real commercial demand. The context makes the stakes legible. Unitree’s shares surged over 65% in the two weeks before the filing, after slumping almost 55% from their August debut; the company issued an abnormal-trading warning on October 21 cautioning investors about valuation risk. Late October even saw a 16.15% single-day rebound that pushed market value back above 200 billion yuan (US$28.1 billion) — volatility that coincides with a broader rout in which Shanghai’s STAR50 chip-and-AI index has lost roughly 40% since July.
One line in the Reuters wire deserves particular attention for what it says about the pipeline: Reuters reported last month that Chinese regulators are slowing IPOs for humanoid robot firms, scrutinising whether soaring valuations and revenue tied to state-backed projects reflect real commercial demand. Unitree’s profit miss gives that scepticism more substance — as we covered when the crackdown emerged, the gatekeeping question is exactly whether these companies can earn, not just raise.
What it means for the sector’s economics
The most useful number for anyone modelling the industry: Unitree booked almost 30% of quarterly revenue in a single month’s worth of R&D, and still calls itself profitable. Its earlier disclosures show this is a company that made its name on cost discipline — the founder’s own cost-cutting and quality push was a public story — so a 250% R&D surge is a deliberate strategic choice, not an accident. The bet is that embodied-intelligence models are the next moat, and that falling behind on model capability would cost more than the spend.
The risk is symmetrical: if model capability becomes the differentiator, then a 127-million-yuan quarterly R&D budget competes directly against the deep-pocketed labs — Physical Intelligence raising $1 billion at $20 billion, FieldAI at $10 billion — whose entire business is that model layer. Unitree’s hardware lead is real; whether a robot manufacturer can fund a frontier-model arms race out of hardware margins is the open question this filing just made unavoidable.
It is also, quietly, a competition story for Western makers: Agibot has already overtaken Unitree in humanoid shipment rankings, and Tesla’s Optimus ramp is accelerating. The first listed humanoid company just told the market what staying ahead costs. Everyone else’s prices are now anchored to that number.